
Reduced Vacancy Slows Leasing Momentum; Luxury Residential Market Remains Resilient
Snapshot for Q3 2026 2026
- Grade A Office: Strong net absorption and falling vacancy continued to improve market fundamentals, while Central led rental growth amid rising demand from financial institutions.
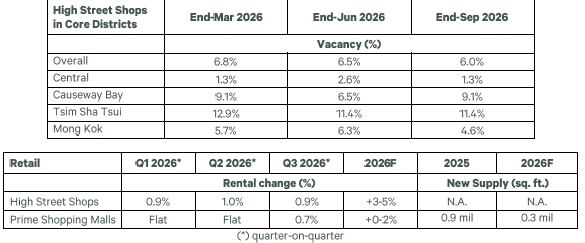
- Retail Leasing: Healthy tourist and consumer spending supported lower high street vacancy and steady rental growth.
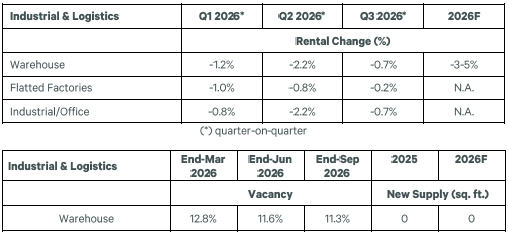
- Industrial & Logistics: Increased rental flexibility, forced relocation activity involving brownfield operators as well as sustained demand from technology-related sectors supported warehouse leasing.
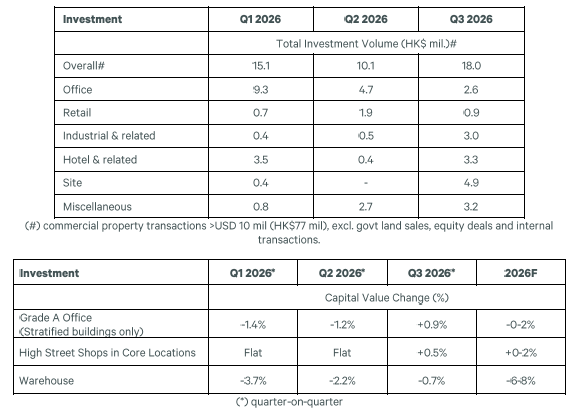
- Investment: Investment activity accelerated, education has emerged to become the most important demand driver this quarter.
- Luxury Residential: Hong Kong’s luxury residential market remained resilient in Q3 2026 despite greater market volatility. Luxury home prices rose 5.3% year-to-date and remained 11.3% above the March 2025 trough.
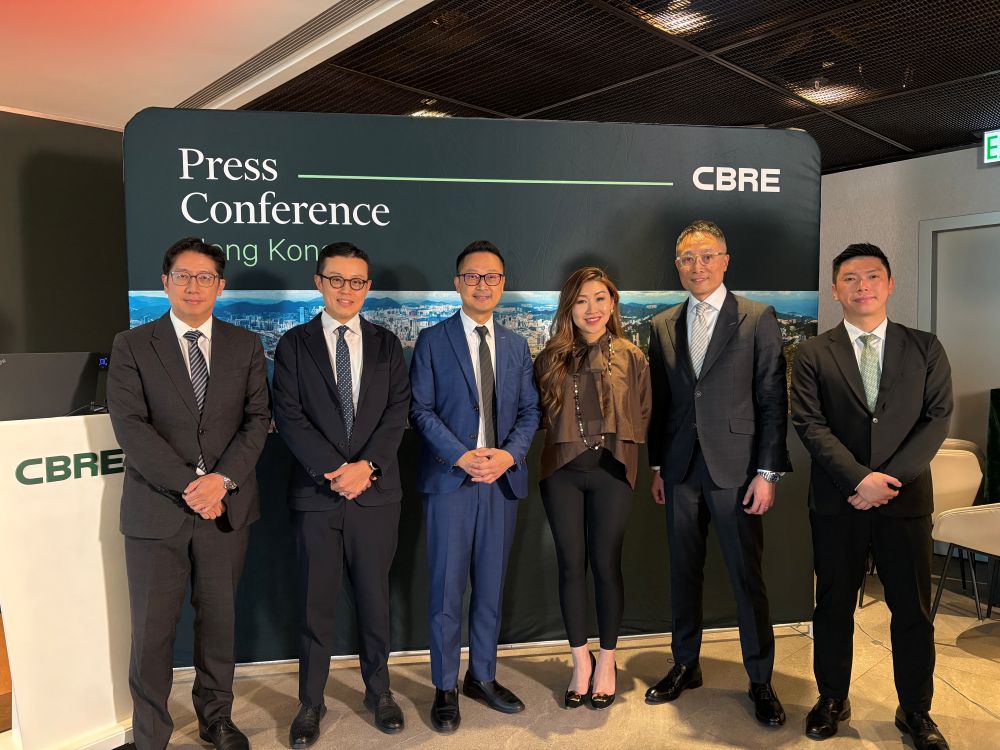
Hong Kong’s commercial real estate market extended its recovery in the third quarter of 2026, supported by robust office leasing activity, declining vacancy rates, stronger investment momentum and continued improvement in the retail sector. The office market recorded its strongest year-to-date net absorption since 2018, while investment transaction volume accelerated amid growing interest from the education sector that drives hotel and other living sector assets while the luxury residential market remained resilient in the quarter, according to CBRE.
“The recovery in Hong Kong’s commercial property market gained further momentum in Q3 2026. Strong office demand from the financial sector and falling vacancy rates in the CBD, coupled with rising investment appetite for education-focused assets, point to improving market confidence that is also backed by Hong Kong’s stronger economic fundamentals. We expect market sentiment to continue improving through the final quarter of the year, despite lingering risks over potential interest rate hikes and stock market volatility,”
said Marcos Chan, Executive Director, Head of Research, CBRE Hong Kong.
Review and Commentaries
Grade A Office
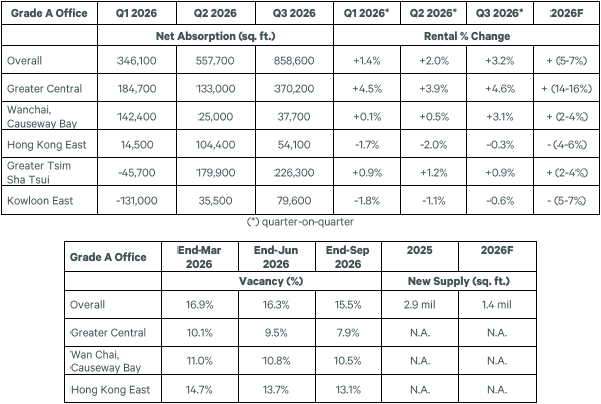
- Gross leasing volume reached 1.2 million sq. ft. in Q3 2026, a drop of 6% quarter-on-quarter. Central accounted for 28% of this quarter’s leasing volume on the back of strong expansionary demand from banking and financial firms, with 73% of activity in the district involving Central A1 buildings. Year-to-date leasing volume reached 3.4 million sq. ft., up 6% year-on-year.
- Citywide quarterly net absorption totalled 858,600 sq. ft., bringing the year-to-date total to 1.8 million sq. ft., the highest first nine-month figure for any year since 2018. Central reported another quarter with net absorption exceeding 200,000 sq. ft. (223,000 sq. ft. in Q3 2026), marking only four such occurrences in the last 20 years. All other major submarkets recorded positive quarterly net absorption; Hong Kong Island contributed 1.2 million sq. ft. of year-to-date net absorption, with 432,500 sq. ft. occurring in Central. Kowloon East was the only submarket to report negative net absorption year-to-date at -16,000 sq. ft., driven by tenant downsizing in Kwun Tong.
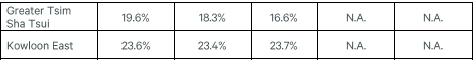
- Despite the addition of one new building in Kowloon East, positive net absorption ensured citywide vacancy fell by 0.8 percentage point to 15.5%, the largest quarterly decline since Q2 2015.
- Lower vacancy supported 3.2% quarter-on-quarter increase in rents. This marked the fourth consecutive quarterly rise and brough year-to-date growth to 6.7%. Central rents rose 15.8% year-to-date, led by a 24.3% increase in Central A1 rents, the strongest growth since Q4 2010. Other core submarkets also recorded growth quarter-on-quarter and year-to-date, although rents in decentralized submarkets continued to fall.
Ada Fung, Chief Operating Officer, Advisory Services, CBRE Hong Kong:
“The office market continued to strengthen in Q3 2026, underpinned by robust leasing demand in Central and the strongest year-to-date net absorption recorded since 2018. Demand from financial institutions remained a key driver, particularly in Central, where sustained occupier activity contributed to further rental growth and declining vacancy. At the same time, occupiers continued to pursue relocation and upgrade opportunities to secure higher-quality space and enhance workplace experience. With vacancy trending lower and business confidence improving, we expect prime office locations to remain best positioned to capture demand and outperform the broader market through the remainder of the year.”
Retail
- Tourist arrivals and retail sales continued to grow in Q3 2026, albeit at a slower pace. Visitor arrivals increased 2.6% year-on-year, adding to 8.7% year-on-year growth registered in Q2 2026. This helped retail sales increase by 4.5% year-on-year in July and 5.6% year-on-year in August, a sixteenth consecutive month of expansion, following 7.1% year-on-year growth in Q2 2026.
- Leasing activity in core districts moderated following a robust Q2 2026, that was the third most active quarter on record. Leasing volume fell 22% quarter-on-quarter to 290,000 sq. ft., bringing year-to-date volume to 883,000 sq. ft., or 77% of 2025’s total. F&B accounted for over one-third of quarterly leasing volume, followed by fitness centres which leased 50,000 sq. ft. across mostly upper-level shops. Activity by fashion brands was confined to Hong Kong Island.
- Vacancy rates for high street shops in core districts fell by 0.5 percentage points quarter-on-quarter to 6.0%, the second lowest level since Q4 2019. Low vacancy contributed to a 0.9% quarter-on-quarter increase in rents, marking the seventeenth consecutive quarterly rise and bringing year-to-date growth to 2.7%.
Lawrence Wan, Executive Director, Head of Retail Leasing, CBRE Hong Kong:
“Hong Kong’s retail leasing market remained on a steady recovery path in Q3 2026, supported by continued growth in visitor arrivals and improving retail sales. Leasing demand was underpinned by both international and mainland Chinese brands seeking opportunities in prime retail locations, while the F&B and lifestyle sectors remained active contributors to market activity. As vacancy in key high street districts continued to decline, landlords gained greater confidence in rental negotiations, supporting moderate rental growth. We expect retail leasing momentum to remain healthy in the coming quarters as tourism and consumer spending continue to recover
- Aggregate trade increased by 51.0% year-on-year in July-August 2026, following a 44.7% increase in Q2 2026. In a shift from recent trends, container throughput improved by 9.9% year-on-year in July-August, but air cargo throughput declined by 1.6% during the same period.
- New leasing volume amounted to 661,700 sq. ft., a drop of 61% quarter-on-quarter from the previous quarter’s high base. Year-to-date leasing volume reached 3.1 million sq. ft., already accounting for 94% of 2025’s volume.
- Brownfield occupiers in the Northern Metropolis provided a steady stream of demand for purpose-built warehouses due to forced relocation. Examples included Kin Keung Transportation Limited leasing 66,800 sq. ft. at ATL Logistics Centre in Kwai Chung.
- Warehouse vacancy dropped by 0.2 percentage point quarter-on-quarter to 11.3%, indicating positive net absorption of 116,100 sq. ft. Warehouse rents fell by a further 0.7% quarter-on-quarter, marking the eleventh consecutive quarterly rental fall. This brough the year-to-date decline to 4.0%
Stanley Yu, Senior Director, Industrial & Logistics, CBRE Hong Kong:
“Hong Kong’s industrial and logistics market continued its momentum in Q3 2026, supported by steady deal flow driven mainly by landlords’ increasing flexibility in rents. The forced relocation demand from brownfield operators also fuelled the market. Warehouse vacancy improved but remains at high level, particularly in and around Kwai Chung, where there is more available space. While rents remained on a downward trend , improving occupancy levels indicate that market fundamentals are gradually stabilising. Looking ahead, we expect lower rentals will continue to drive steady deal flow in Q4 2026, although rental recovery is likely to remain gradual and vary by location and asset quality.”
Commercial Real Estate Investment
- The Fed hiked the U.S. federal funds rate by 25bps to 3.75%-4.00% this quarter, marking the first increase since 2023. While major banks kept prime rates unchanged, the benchmark one-month HIBOR rose from 2.94% on June 30, 2026 to 3.01% on September 30, 2026, the highest quarter-end level since Q4 2025. Negative yield carry conditions associated with many commercial properties continue to persist.
- Investment volume * reached HK$18.0 billion in Q3 2026, a rise of 79% quarter-on-quarter. Investors retained a strong interest in student accommodation conversion opportunities, deploying HK$5.3 billion into the sector during the quarter. Highlights included Singapore’s CapitaLand Investment acquiring ibis Hong Kong Central & Sheung Wan for HK$2.3 billion for conversion, and Chinese e-commerce company JD Group purchasing two hotels in Yau Ma Tei and Wan Chai for a total of HK$1.03 billion. Market-wide year-to-date investment volume* reached HK$43.2 billion, achieving 94% of 2025’s total volume.
- Development sites at strategic locations remained sought after by property developers. During the quarter, a residential site at 992-998 King’s Road in Quarry Bay was transacted for HK$4.5 billion.
- Other highlights included Amazon Web Services’ purchase of two data centres, iTech Tower 3.1 and iTech Tower 3.2 in Fanling for up to HK$2.45 billion as it turned from a tenant into an asset owner.
- The number of deals* recorded in Q3 2026 was 34, with 16 of them involving financially stressed assets transacted for an aggregate of HK$7.8 billion.
*deals involving commercial real estate over HK$77 million.
Avan Pau, Senior Director, Capital Markets, CBRE Hong Kong:
“Investment activity accelerated in Q3 2026, with transaction volume rising significantly. The quarter experienced a broader range of investment interest, with non-local private and institutional investors contributing the highest capital in two and a half years, highlighting the growing confidence of investors in Hong Kong. Emerging asset classes such as education-linked properties and data centres became increasingly attractive to both local and global investors. While higher yield expectations and ongoing challenges in securing bank financing will continue to pose difficulties for the market, improving market fundamentals and a promising outlook in the education and tech sectors offer investors compelling reasons to invest. We expect investment activity to remain active through the remainder of the year.”
Luxury Residential
- Hong Kong’s luxury residential market remained resilient in Q3 2026 despite greater market volatility. Luxury home prices rose 5.3% year-to-date and remained 11.3% above the March 2025 trough.
- Ultra-luxury demand stayed strong, with 197 transactions above HK$100 million recorded in the first three quarters of 2026, up 109.6% year-on-year. Total consideration increased 54.9% to HK$28.2 billion.
- Mainland Chinese buyers continued to drive activity, accounting for 72% of primary market transactions and 68% of secondary market transactions in Q3.
- Limited supply of prime residential assets and strong demand from mainland China remains a key support for the market
Eddie Kwok, Executive Director, Valuation & Advisory Services, CBRE Hong Kong:
“Hong Kong’s luxury residential market has remained resilient despite interest rate uncertainty and tighter capital controls. Demand from high-net-worth buyers, particularly from mainland China, continues to support activity in the ultra-luxury segment, while limited new supply underpins values in prime locations. We expect luxury residential prices to remain broadly stable through the remainder of 2026
Outlook
Hong Kong’s real estate market entered the final quarter of 2026 with improving momentum across both occupier and investment markets. Strong office absorption, declining vacancy rates, resilient retail leasing demand and rising investment activity point to a broadening recovery underpinned by improving business confidence and economic fundamentals. While global economic uncertainty and financing costs remain factors to monitor, Hong Kong continues to benefit from its position as a leading international financial centre, growing capital market activity and ongoing integration with the Greater Bay Area. We expect leasing and investment activity to remain healthy through the remainder of the year, with prime and well-located assets likely to attract interests.