
Cross-border investors account for nearly two-thirds of transactions as structural supply shortages and resilient demand reshape the sector’s investment appeal
Key Takeaways
- Transaction volumes have tripled since 2022, with cross-border investors accounting for around two-thirds of student housing transaction activity in 2025.
- Hong Kong’s projected 140,000-bed student accommodation shortfall by 2029/30 is driving investment into PBSA and hotel conversions.
- Long-term demand from rising international student mobility and persistent supply constraints is expected to support sustained investment activity, rental growth and market expansion across the region.
The Asia Pacific student housing sector is undergoing a fundamental transformation, with transaction volumes tripling since 2022 as cross-border institutional investors increasingly dominate the market. According to JLL, the surge in cross-border investment activity reflects a broader institutional repricing of the sector, driven by structural demand dynamics and persistent supply constraints that are reshaping the risk-return profile of student housing across Asia Pacific.
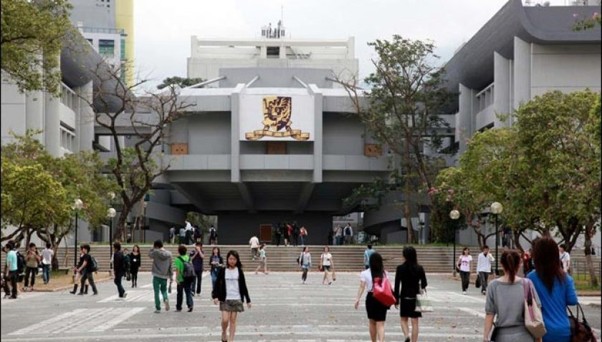
Hong Kong is emerging as a key market within the region’s evolving student housing landscape. The city’s ambition to become a global education hub, coupled with a chronic shortage of purpose-built student accommodation (PBSA), is driving significant capital deployment. This momentum is exemplified by landmark transactions such as Centaline Strategic Investments’ HKD1.51 billion acquisition of the Regal Oriental Hotel in Kowloon City for conversion into a student hostel.
Cathie Chung, Senior Director of Research at JLL in Hong Kong, said:
“As Hong Kong aspires to become a leading international education destination, student accommodation has emerged as one of the city’s most pressing real estate challenges. The acute supply-demand imbalance, underscored by a projected shortfall of more than 140,000 student beds by 2029/30, is accelerating capital deployment into alternative solutions, most notably the conversion of existing hotels into PBSA. For investors, the sector presents a compelling opportunity underpinned by resilient demand and income visibility that is largely insulated from broader real estate market cycles.”
While localised strategies such as hotel conversions gain traction in Hong Kong, the sector’s broader defensive characteristics are attracting significant foreign capital across the region. In 2025, cross-border investors accounted for approximately two-thirds of total student housing transaction volume, with activity concentrated primarily in Australia, the region’s most accessible and mature market. By contrast, domestic capital represented 54% of overall Asia Pacific living sector transactions in 2025, highlighting the strong global appeal of student housing as an asset class.
JLL data and analysis show that private equity dominated regional investment activity over the past two years, with Australia absorbing the majority of deployed capital. However, H1 2026 marked a notable shift, with listed REITs emerging as the most active buyers in the segment, signalling growing confidence from traditional real estate capital.
Lauren Hetherington, Senior Director, Living Capital Markets Asia at JLL, said:
“Structural demand continues to position student housing as one of the most compelling long-term investment opportunities in Asia Pacific. Our conviction is reinforced by the steady diversification of the buyer pool since 2022, with increased participation from developers, listed and unlisted REITs, fund managers and education companies. Fundamentally, this broadening capital base reflects the asset class’s transition into the institutional mainstream, moving beyond its origins as a specialist, niche investment opportunity.”
JLL believes the investment case for Asia Pacific student housing will be further supported by durable demographic and policy shifts reshaping global student mobility. With the number of internationally mobile students projected to reach 9 million by 2030, the demand surge is occurring against a backdrop of structural supply shortages. Unlike cyclical inventory gaps, the region’s accommodation deficit is deeply embedded, supporting rent growth regardless of broader market conditions and providing downside protection for investors.
Despite the region-wide momentum, JLL’s analysis indicates that student housing markets across Asia Pacific are maturing at different rates, requiring investors to adopt market-specific strategies. For the foreseeable future, Australia is expected to remain the gateway market for global capital targeting the student housing sector. Other markets across the region offer opportunities for scale and first-mover advantage, but require differentiated approaches that account for varying levels of market maturity, regulatory frameworks and operational complexity.