
Savills’ latest Investment Market in Minutes highlighting how demand for student accommodation and school expansion is opening new channels for property investment. Transactions exceeding HK$50 million totalled approximately HK$50.7 billion in the year to 22 October, with education-related acquisitions accounting for around HK$17 billion, or 33%. Investors from Singapore and elsewhere in Southeast Asia are actively exploring accommodation assets, while institutional and owner-occupier buyers continue to support selected transactions. Most recently, Malaysia’s ParkCity acquired the Sheraton and Four Points Tung Chung asset for a reported HK$2.7 billion. However, the market has yet to see a broad-based recovery, with property suitability, conversion costs and financing conditions remaining critical to investment returns. For details, please refer to the attached report for further insights.
- Education-related investment accounts for approximately 33% of large-ticket transactions
Property transactions exceeding HK$50 million totalled approximately HK$50.7 billion in the year to 22 October 2026, including apartments. Excluding apartments, non-residential transaction consideration reached approximately HK$44.15 billion. Education-related acquisitions represented around 33% of total consideration, demonstrating the growing role of student accommodation and teaching space in supporting investment activity. Against an uneven recovery in commercial rents, institutions and owner-occupiers are focusing on assets with clear operational uses or credible conversion potential. - Student housing drives accommodation asset repositioning and attracts regional capital
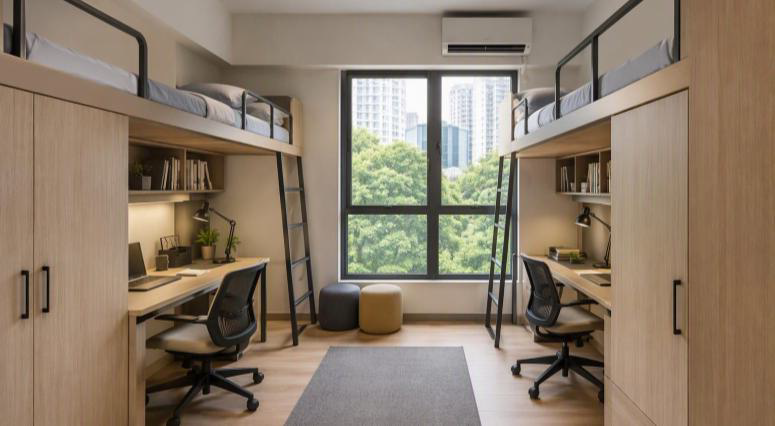
Of the 19 hotel and serviced apartment transactions recorded from January to October 2026, 15 were intended for conversion to student accommodation, involving approximately HK$7.9 billion in consideration. Singaporean investors and accommodation operators have been active, with transactions including Centurion Corporation’s acquisition of Yan Wo Building in North Point and Wee Hur Holdings’ purchase of One Bedford Place in Tai Kok Tsui. Demand from non-local students and insufficient purpose-built supply are creating opportunities to reposition suitable properties. However, intended use does not mean conversion is complete or operations have commenced. Returns depend on location, room configuration, approvals, refurbishment costs and the time needed to achieve stabilised occupancy. - School expansion brings long-term tenants to retail and commercial properties
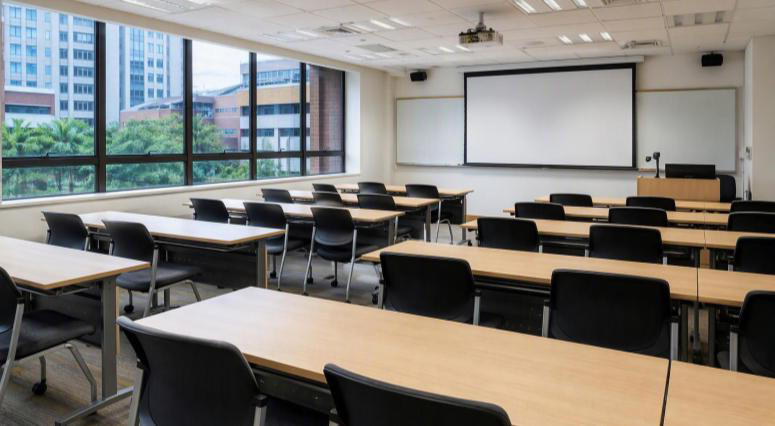
International schools and education providers are seeking office podiums in non-core locations and suburban retail premises near existing campuses to accommodate additional teaching and ancillary facilities. Five education leasing transactions highlighted in the report, spanning September 2025 to August 2026, involved approximately 208,000 sq ft in total. These included Kellett School’s lease of approximately 45,272 sq ft at The Bay Hub and Tianli Education’s lease of approximately 36,400 sq ft in the retail portion of One HarbourGate. Long leases to credible education providers can improve income stability, although permitted use, access arrangements and fit-out expenditure remain essential considerations. - Institutions and owner-occupiers support transactions, while commercial and industrial performance remains mixed
Office investment consideration reached approximately HK$27.46 billion in the year to 22 October, representing around 54.2% of total large-ticket property transaction value. Nevertheless, Central strata-title office transactions fell from 17 in Q2 to eight in Q3. Industrial transaction volumes also declined, from 721 in Q2 to 583 in Q3, a quarter-on-quarter decrease of 19.1%. Selected repriced assets continued to attract owner-occupiers, including the Hong Kong University of Science and Technology’s HK$141 million acquisition of Pricerite Centre Building in Sai Kung. Such transactions illustrate how operational requirements can support purchases even when conventional investment demand remains cautious. - Diverging capital values place greater emphasis on sustainable net income and financing resilience
Mass residential and luxury townhouse capital values rose by 0.8% and 0.5% quarter-on-quarter in Q3, respectively, while retail, office and logistics values declined by 0.6%, 0.9% and 5.0%. These contrasting movements indicate that a broad-based recovery has yet to emerge. Looking ahead to Q4 2026 and 2027, opportunities are expected to remain concentrated in assets offering identifiable occupier demand, viable conversion plans and disciplined entry pricing. Financing and refinancing pressures could bring more discounted properties to market, but buyers must account for operating expenditure, capital investment and vacancy periods when assessing whether net income provides an adequate buffer over funding costs.
Mr. Jack Tong, Director, Research & Consultancy of Savills commented,
“Education is emerging as one of the clearer sources of new demand in Hong Kong’s property investment market, supporting both student accommodation conversions and long-term lettings in selected retail and commercial properties. However, growth in education-related transactions does not signal a market-wide recovery. Investors need to distinguish an individual asset’s operational potential from wider sector trends and assess its value against sustainable net income after conversion and operating costs.”
Mr. Peter Yuen, Managing Director, Investment & Sales of Savills said,
“Today’s market places greater weight on practical use and cash flow than on capital appreciation alone. For well-capitalised investors, repricing and the refinancing needs of individual owners may create selective acquisition opportunities. Whether considering student accommodation, properties with long-term education tenants or commercial and industrial assets for owner-occupation, buyers should maintain pricing discipline and allow sufficient buffers for capital expenditure, vacancy and funding costs.”
Mr. Godfrey Cheng, Senior Director, Head of Chief Investment Office at Savills Hong Kong said,
“The correction in Hong Kong property prices is encouraging investors from Singapore and elsewhere in Southeast Asia to reassess opportunities in accommodation assets. Buyers with specialist operating experience are particularly interested in properties that can generate recurring income or improve their utilisation through repositioning. While student accommodation demand is clear, successful investment still depends on the right acquisition price, a viable approvals process and effective management of conversion costs and delivery timelines.”