
The ongoing US-China trade war and uncertain global economic outlook will weigh on the prices and rents of residential and commercial properties in the second half of 2019, according to JLL’s Mid-year Property Market Forecast released today. The recent protests and social unrest may also have some short-term negative impacts on Hong Kong’s inbound tourism market, which may affect retail sales, but any sustained impact on the residential market will be limited and temporary.
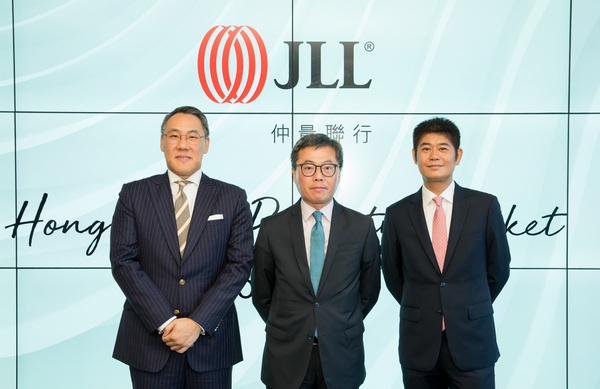
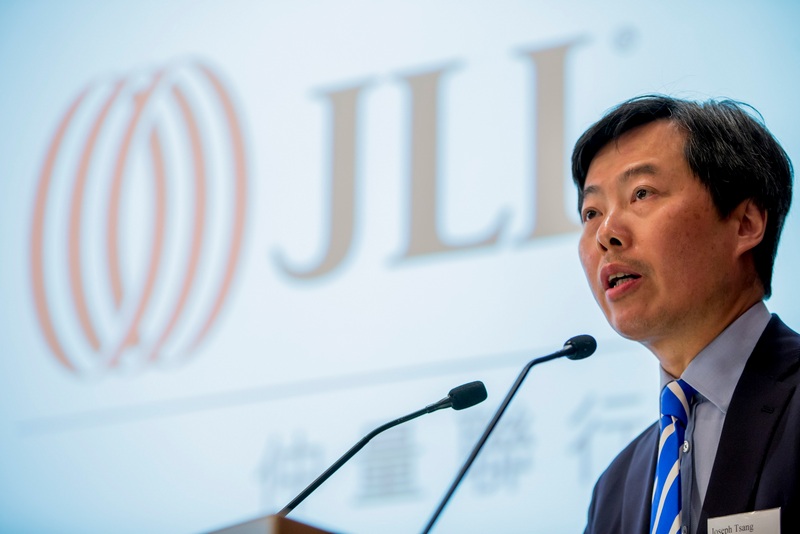
(Left to right) Paul Yien, Joseph Tsang, Terence Chan
Highlights of the briefing:
- New lettings from PRC firms in Central down 53% y-o-y in the first half.
- Central’s Grade A office rents edged 0.1% q-o-q lower in the second quarter, the first recorded quarterly fall since the fourth quarter of 2013.
- Office rental market has peaked; Central’s rental market to face increasing downward pressure.
- Rents of high street shops to retreat by up to 3% in the second half.
- The uncertain economic outlook to dampen buying sentiment in residential market.
- Up to 16,000 units to be launched for sale in the second half.
- Prices of residential properties to drop 0-5% in 2019.
Office Market
Leasing demand in the overall market was subdued in the first half of 2019 as corporate occupiers curtailed expansion plans amid ongoing uncertainties in the global economy and US-China trade war. New lettings during the period dropped by 11% compared to the second half of 2018.
PRC firms, the key driver of demand in Central over the last three years, turned inactive through the first half with new lettings from PRC firms falling 53% y-o-y. Tenant decentralistation remained a major demand driver in the market as firms continued to focus on managing costs.
Easing demand along with the completion of new supply contributed to the overall vacancy rate at the end of June moving above 5% for the first time since early 2018. Rising vacancy rates in Central and Tsimshatsui were attributed to leasing demand falling below replacement levels.
The uncertain outlook on leasing demand led to some landlords in Central and Wanchai/Causeway Bay lowering rents to accelerate the backfilling of space left by decentralising tenants. As a result, Central’s Grade A office rents edged 0.1% q-o-q lower in the second quarter, the first recorded quarterly fall since the fourth quarter of 2013. Rents in Wanchai/Causeway Bay were down 0.4% q-o-q during the same period.
Paul Yien, senior director of HK Markets at JLL, said: “The recent protests did not dampen the interests of multi-national companies to expand to Hong Kong. But we saw several occupiers who were experiencing disruption to their day to day business consider continuity plans around their real estate requirements in the city. However, this turned out to be temporary, with their concerns easing after the protests ended.”
“Looking forward, with leasing demand to remain soft, vacancy rates will continue to rise. We believe the rental market has peaked and will continue to moderate in the second half of 2019 with Central’s office rents to face the greatest downward pressure. However, the tight vacancy rate will allow landlords to ease rents gradually. For the year as a whole, most of the city’s rental markets should still end the year up slightly except for in Kowloon East where rents are forecasted to retreat 0-5%,” he added.
Retail Market
The city’s inbound tourism market continues to benefit from the opening of new cross-border transportation links, with visitor arrivals up 14.9% y-o-y through the first five months of the year. However, the surge in visitor arrivals has failed to translate into stronger sales with total retail sales down 1.8% y-o-y during the same period. While sales of most major trade categories shrunk, F&B and department stores sales still recorded notable growth. Total restaurant receipts were up 3% y-o-y for 1Q19 while department stores rose by 2.8% y-o-y for the first five months of the year.
Lacklustre sales curbed the enthusiasm of retailers to open new stores, especially on the city’s high streets. As a result, shop rents along the high streets in the city’s four key shopping precincts dropped 1.9% y-o-y in the first half while those in Central fell by 6.9% y-o-y. The inability of landlords to push high street shop rents was also compounded by new market entrants continuing to show a preference towards opening stores in shopping centres; simultaneously providing support for overall prime shopping centres rents.
With the retail sector continuing to struggle, landlords are increasingly open to accommodating different concepts and anchor tenants, as a point of differentiation. This trend can be seen in the general uptick in leasing commitments for sizable shops of over 10,000 sq ft in the first half. With a flurry of new prime shopping centres set to complete between 2019 and 2023—annual average will be 56% higher than the historic 10-year average—the market is set to provide more opportunities for larger-store retailers.
Terence Chan, senior director of retail at JLL, said: “The US-China trade war and recent social unrest has cast a shadow on the city’s retail sector and is likely to further weigh on retail sales through the rest of this year. This in turn will put pressure on rents. For the year as a whole, we expect high street shop rents to correct by about 5%. Prime shopping centre rents, on the other end, should be able to hold steady to post flattish growth.”
Residential market
Average monthly residential sales increased to 5,753 over the first half of the year, the highest level in five years. The uptick was mainly supported by new homes sales which continue to be inadvertently supported by the government’s demand suppression measures for the city’s housing market. Lower Loan-to-Value ratios together with decreasing affordability have essentially pushed buyers towards the primary market.
The volume recovery led to capital values of mass residential increasing 3.9% in the first half of 2019 and reversing much of the correction recorded in the second half of 2018. Capital values of luxury residential properties increased by 4.0%.
Looking ahead, up to 16,000 units are expected to be launched for sale in the second half of this year, the most in a half year over the past three years. The increase of new launches is likely to limit the ability of developers to continue to raise asking prices, especially in the New Territories where around 60% of new launches will be concentrated.
Joseph Tsang, chairman and head of capital markets at JLL in Hong Kong, said: “Despite recovering through the first half, we continue to hold a negative outlook for the city’s residential property market over the short-to-medium-term. The difficulties in resolving the ongoing trade war and slowing global economy will ultimately offset the potential of any interest rate cuts to dampen buying sentiment. Coupled with the increase of new launches in the second half and looming vacancy tax, developers will need to adopt a more accommodative pricing strategy if they wish to maintain sell through rates”.
“Amid the better-than-expected first half of this year, we maintain our view for capital values of mass and luxury residential properties to correct in the second half of the year with flattish full-year growth and risks on growth towards the downside,” Tsang added.
Investment market
A total of HKD 53.3 billion (for transactions over HKD20 million) was invested into the city’s commercial and industrial property markets in the first half of 2019. Although the amount was 51% less than a year ago, it was still comparable to levels recorded from 2014 through to 2017. PRC buyers continued to be largely sidelined, participating in only eight deals and contributing to just 15% of total volumes during the period, down from 21% in 2018.
Office properties remained the most popular asset class for investors, accounting for 57% of all transactions during the period. Investors, however, were primarily focused on assets in office markets in decentralised locations.
The drop in volumes was largely attributed to the negative outlook for rental markets, especially office and retail where rents started showing signs of softening in the first half of the year and leading to capital values of Grade A offices and High Street Shops retreating by 0.6% and 3.8%, respectively, in the first half of this year.
Industrial properties remained as a bright spot with capital values of Flatted Factories increasing by 2.4% and Prime Warehouses increasing by 3.5% as investors sought to capitalise on the relaunch of the government’s industrial building revitalisation scheme. Capital values of Flatted Factories surged by about 160% from 2010 until the end of 2015 after the government first introduced the scheme.
Joseph Tsang said: “Uncertainties in the local and global economy together with slowing rental markets is driving investors towards segments of the market where there is still room for growth. The investment potential of industrial properties is the most optimistic, thanks to the government’s revitalisation industrial policy and low vacancy for prime warehouse stock. In the office sector, investors are now focusing on assets in locations that may benefit from tenant decentralisation, such as Hong Kong East and Kowloon East. While in the retail sector, investors continue to target neighborhood malls in areas with significant increases in resident populations”.
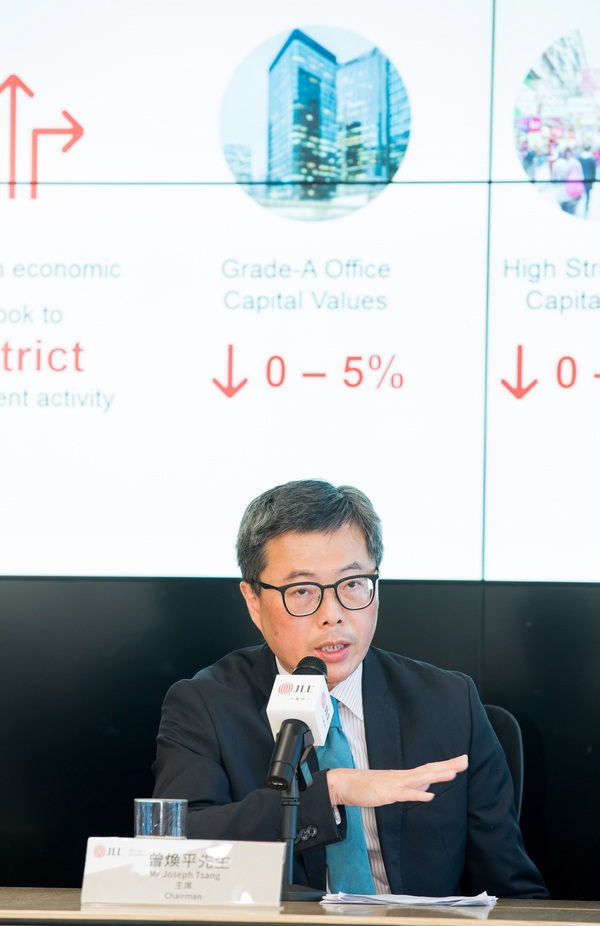
“PRC investors has become less active in Hong Kong’s investment market since the central government tightened capital outflows. For the remainder of the year, it is hard to see how the current market situation will reverse and as such we believe capital values of Grade A office and high street shops will drop 0-5% while those of prime warehouse should outperform the market and grow 0-5% this year,” he added.